By John Vandermosten, CFA
NYSE:PLX
READ THE FULL PLX RESEARCH REPORT
Second Quarter 2023 Financial and Operational Review
Protalix Biotherapeutics, Inc. (NYSE:PLX) announced 2Q:23 financial and operational results in an August 7th, 2023 press release and filing of Form 10-Q. The reports were followed by a conference call which discussed recent achievements, regulatory updates and financial performance. Since Protalix’ previous quarterly update on May 4th, many positive events have taken place that have, without a doubt, increased the value of the company compared to where it was three months ago. Elfabrio’s approval by the European Commission for marketing in the European Union, approval by the FDA for marketing in the United States and a $20 million milestone payment from partner Chiesi were announced. Protalix was also added to the Russell 3000 in late June, opening up the company’s shares to be owned in a variety of index funds.
In addition to these material events, management also announced attendance at investor conferences and held a key opinion leader (KOL) event in early June. The event featured the head of Chiesi Rare Disease, Giacomo Chiesi, and nephrologist Ankit Mehta, MD to discuss the commercialization framework and opportunity for Elfabrio.
Following the two approvals in the EU and US, Chiesi began to build inventories and commence first sales of Elfabrio. Protalix has recognized its approval milestone and product revenues for Elfabrio in the second quarter. Revenues for 2Q:23 were $35.1 million, which was comprised of a $20 million milestone, $11.7 million in revenues from Chiesi and $3.4 million in revenues from Pfizer. This resulted in net income of $19.3 million versus a net loss of ($5.3) million in 2Q:22.
Financial results for the quarter ending June 30, 2023, compared to the quarter ending June 30, 2022:
➢ Revenues were $35.1 million, up 301% from $8.7 million; as a slight increase in Elelyso sales to Pfizer were augmented by an $11.7 million contribution from Chiesi to build inventory for Elfabrio. $20 million in regulatory milestones were recognized related to the new approval. No sales were reported for Brazil’s Fiocruz in the quarter;
➢ Cost of revenues was up 50% to $6.1 million producing a 59% gross margin on goods sold which was better than the -21% gross margin in the comparison period. The change was attributable to the contribution of Elfabrio sales to Chiesi and royalties payable to the Israel Innovation Authority in connection with the Chiesi agreements;
➢ Research and development expenses fell 41% to $4.5 million from $7.6 million. Lower spending on the Fabry clinical program and regulatory process related to filing the BLA and MAA contributed to the change;
➢ Selling, general and administrative expenses rose 54% to $4.0 million vs $2.6 million. The increase was related to higher salary and related expenses due to one-time cash bonuses;
➢ Net financial expense was ($0.8) million compared to a contribution of $0.2 million due to unfavorable exchange rates and an increase in convertible notes related expenses due to conversions;
➢ Net income was $19.3 million vs ($5.3) million, or $0.21 per share versus ($0.11) per share;
Cash and equivalents balance on June 30, 2023 totaled $48.2 million versus $22.2 million at the end of 2022. Free cash flow was $1.5 million for the first six months of the year. Financing cash flows were $10.4 million predominantly related to proceeds from issuance of common stock through an at-the-market (ATM) facility. Year to date, Protalix sold 12.6 million shares from the ATM, with an additional increase in share balance of 4.7 million shares from convertible note conversions and 0.5 million from warrant exercises. Protalix estimates that it holds sufficient cash to fund operations for at least the next 12 months.
KOL Event
On June 27th, Protalix held a key opinion leader (KOL) event to discuss Elfabrio, for the treatment of adults with confirmed Fabry Disease. Protalix CEO Dror Bashan introduced the event and its featured KOL, Dr. Ankit Mehta, of Baylor University Medical Center, Dallas, Texas and the head of Chiesi Rare Disease, Giacomo Chiesi. The one hour and forty-minute event was broken into three segments including a discussion of Fabry Disease and Protalix’ related trials, a presentation by Mr. Chiesi relating his company’s history, business units and rare disease unit as well as a review of Protalix’ strategic future and its in-development portfolio. Details of the event and a replay are available here.
Conservative Back of the Envelope Math Suggests Dramatically Higher Valuation
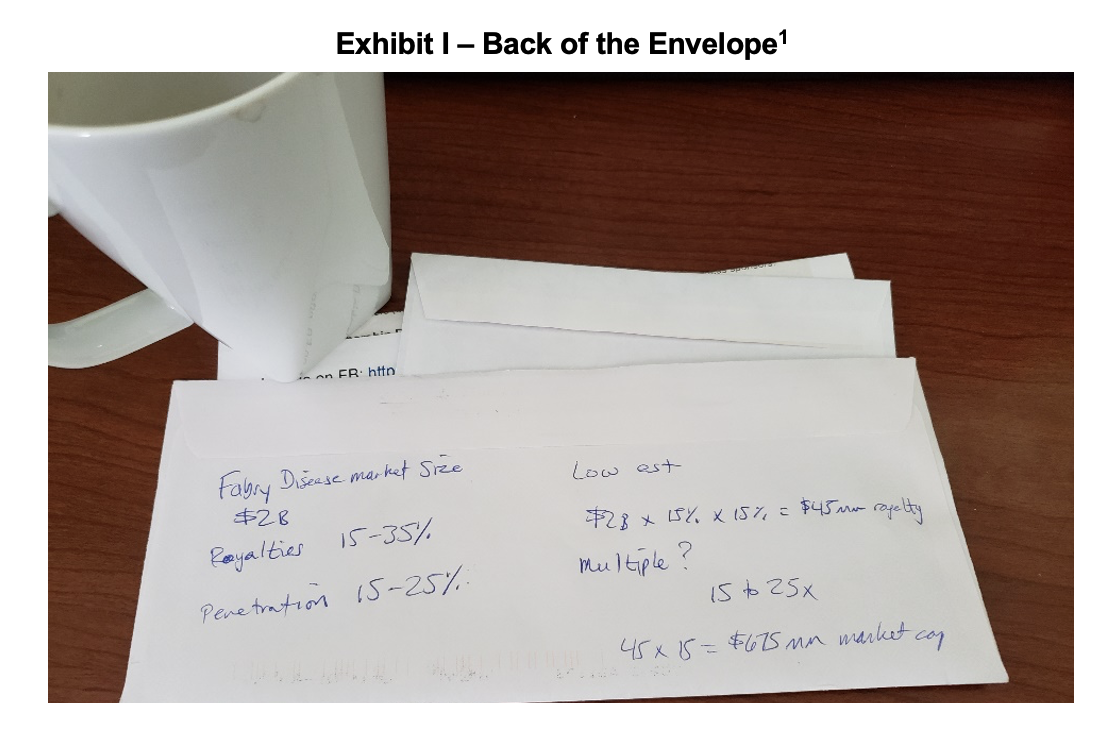
In response to the unexpected decline of Protalix’ share price to several materially positive announcements, we conducted a back of the envelope analysis of the company’s value based on conservative assumptions which showed a very favorable upside to current levels. This is not our official valuation, but it is an attempt to show that even under a low-end scenario, Protalix’ shares are undervalued. We begin with a review of share price movements aligned with the company’s announcements.
On May 4th, Protalix closed at $3.36 per share, equivalent to a market capitalization of about $216 million. The next day, on May 5th, the European Commission (EC) granted marketing authorization to PRX-102 (Elfabrio) in the European Union. On May 10th Protalix announced that FDA approval had been granted to Elfabrio. This was followed by Protalix’ announcement that a $20 million milestone would be paid in the next 30 days by commercialization partner Chiesi. Furthermore, on May 19th, Protalix was included in the new group of companies set to join the Russell 3000 Index on June 26th, a status that is associated with mandated purchases by index funds.
Closing share price and event:
➢ $3.36 – day before EC approval granted (May 4)
➢ $3.27 – EC approval announced (May 5)
➢ $2.92 – day before FDA approval granted (May 9)
➢ $2.94 – FDA approval announced (May 10)
➢ $2.36 – day before milestone announced (May 17)
➢ $2.14 - $20 million milestone announced – payable in 30 days (May 18)
➢ $2.06 – Friday’s closing price (May 26)
Obtaining regulatory clearance in the United States and European Union is a long, painstaking and uncertain process. So, when it is granted, not only does it allow the candidate to generate sales, but it also reduces the risk profile of the product. Based on our comprehensive review of research efforts regarding probability of success for a candidate submitted to the regulatory authorities, we estimate an approximate 85% chance of approval when a biologics license application (BLA) is submitted. When approval is granted, this moves to 100% supporting a share price increase of about 18%, all else equal.
We performed a quick and reserved back of the envelope analysis to generate a base case valuation.
➢ Fabry Disease market size – $2 billion2
➢ Potential market share – 15% – 50%
➢ Royalty from Chiesi – 15% to 40%
➢ Applied multiple of royalty revenues – 15x – 25x
➢ Convertible debt – rounded up to $30 mm
If we take the low end of each of these components and calculate a value, this produces a conservative enterprise value estimate of about $675 million. After subtracting convertible debt this gives us an equity value of $645 million or about $10 per share.
$2 billion x 15% market share x 15% royalty = $45mm. $45mm x 15x valuation multiple - $30mm debt = $645mm.
This back of the envelope approach assumes that no value is attributed to the development portfolio (PRX-115 & PRX-119), no value is attributed to Elelyso, that market share will not exceed 15% and that royalties will never rise above the bottom tier and no further milestones will be paid.
We believe Elfabrio will be able to take share from other enzyme replacement therapy (ERT) alternatives such as Replagal and Fabrazyme. Elfabrio offers:
➢ Better median reduction in the eGFR slope as demonstrated in the BALANCE study (not statistically significant);
➢ Reduction in eGFR slope for duration of Elfabrio treatment after previous treatment with Fabrazyme in BRIDGE study;
➢ Reduced use of infusion pre-medication and fewer infusion-related reactions;
➢ Lower neutralizing antibody activity at end of study;
➢ Potential for periodicity of dose administration every four weeks vs. every two weeks for approved products.
Our Low-end Valuation Assumptions
Our target price and valuation are determined using a set of more realistic assumptions that produce a $16 target which we recently increased following the FDA approval of Elfabrio. These assumptions include peak penetration of 18% of US and ex-US markets, as well as a sum of royalty and milestone payments of up to 40% of product revenues.
Elfabrio Approval
The FDA announced approval of Elfabrio, effective May 9, 2023, making it the 15th approved drug for the year from the US agency. Elfabrio, previously designated PRX-102, is indicated for long-term enzyme replacement therapy in adult patients with a confirmed diagnosis of Fabry disease (deficiency of alpha-galactosidase). Protalix Biotherapeutics celebrates two approvals in less than a week with the European Medicines Agency, providing its authorization for the product on May 4th, 2023. In an early morning press release on May 5th, 2023, Protalix along with Chiesi Group Global Rare Diseases announced that the European Commission had approved PRX-102.
PRX-115
In March 2023, Protalix announced that it had dosed its first patient in the Phase I clinical trial for PRX-115 in the treatment of severe gout. It is designed as a double-blind, placebo-controlled, single ascending dose study intended to evaluate the safety and pharmacokinetics, pharmacodynamics and immunogenicity of PRX-115. Subjects will present elevated uric acid levels (>6.0 mg/dL) and no previous exposure to PEGylated uricase. The single ascending dose study will have up to seven cohorts with patients randomized 3:1 to receive a single intravenous dose of PRX-115 or placebo. Other secondary endpoints will examine the reduction in uric acid and dosing efficacy. The study is being conducted at New Zealand Clinical Research under the New Zealand Medicines and Medical Devices Safety Authority. Further details on the clinical trial can be found on clinicaltrials.gov and the related entry under NCT05745727.
As of early August, 16 patients have been dosed in the trial and a total of 56 subjects are expected to be enrolled. The trial is slated to be complete by end of year 2023 or early 2024. Final results are anticipated in the second quarter of 2024.
PRX-119
PRX-119 is the plant cell-expressed PEGylated recombinant human DNase I product candidate being designed to elongate half-life in the circulation of the molecule for NETs-related diseases. Protalix has conducted preclinical studies to evaluate the feasibility of the candidate. We expect to hear additional details regarding PRX-119 at the investor day planned for June 2023.
SUBSCRIBE TO ZACKS SMALL CAP RESEARCH to receive our articles and reports emailed directly to you each morning. Please visit our website for additional information on Zacks SCR.
DISCLOSURE: Zacks SCR has received compensation from the issuer directly, from an investment manager, or from an investor relations consulting firm, engaged by the issuer, for providing research coverage for a period of no less than one year. Research articles, as seen here, are part of the service Zacks SCR provides and Zacks SCR receives quarterly payments totaling a maximum fee of up to $40,000 annually for these services provided to or regarding the issuer. Full Disclaimer HERE.
________________________
1. Zacks Analyst Work
2. According to Evaluate Pharma, annual sales in the Fabry Disease indication were $1.9 billion in 2022 and are expected to be over $2 billion by 2024 and are expected to grow from 6-10% per annum over the next five years.