By M. Marin
NYSE: CXW
READ THE FULL CXW RESEARCH REPORT
Strong operating improvements, guidance increased
CoreCivic (NYSE: CXW) reported 3Q26 results last week, with total revenue of $744.1 million up 28.2% year-over-year compared to revenue of $580.4 million reported in 3Q25. The increase primarily reflected higher federal and state populations and occupancies, including at recently reactivated facilities, combined with the benefit of contribution from CXW’s acquisition of Clinical Solutions Pharmacy (CSP) earlier in the year. The company has multiple previously idled facilities in various stages of reactivation, contributing to occupancy levels reaching 84.0% in 3Q26 from 76.7% in 3Q25 and 78.4% in 2Q26. Excluding non-recurring items, including those associated with asset sales and the CSP transaction, the company recorded 3Q26 adjusted EPS of $0.49 compared to $0.24 in 3Q25. The company reported Normalized Funds From Operations (FFO) of $0.75 per share, compared with $0.48 in 3Q25. Adjusted EBITDA was $117.8 million, up from $88.8 million in 3Q25.
Believe asset sales de-risk CXW fixed asset exposure, facilitate growth measures
Importantly, CXW sold four facilities to government partners during 3Q26, producing aggregate gross proceeds of $2.2 billion and a $1.8 billion gain on sale of real estate assets. CXW expects to continue to manage the facilities under contracts with ICE, with contract terms potentially modified to reflect the change in ownership, although we would expect potential contract modifications to have minimal impact on CXW’s EBITDA and cash flow metrics, with potentially lower fees or per diems likely largely offset by anticipated declines in aggregate facility maintenance and other spending.
We view it positively that CXW has monetized these assets with little to no expected impact on cash flow and believe the asset sales de-risk CXW’s exposure to ICE somewhat, which we also view positively, although ICE is funded through 2029. Moreover, we also view CXW's diversification efforts, with the recent CSP and potentially other bolt-on acquisitions, while its book of existing and potential business is robust, as a positive aimed at enabling future growth opportunities.
Moreover, CXW is also engaged in discussions with ICE about potential sales of additional facilities. CXW facilities are purpose-built for the needs of ICE and other government entities. CXW facilities generally are modern and designed to provide services that could make them a turnkey solution for government agencies. It would not surprise us if the recent mid-term election results accelerated some conversations around this sale-management contract model.
We believe the cash infusion from asset sales enables CXW to make additional tuck-in acquisitions in adjacent service sectors opportunistically, which we view as another positive. For example, recently acquired CSP is one of the largest domestic providers of mail order pharmacy services to correctional facilities. CSP serves 600+ correctional facilities across 28 states, including CXW’s. The acquisition helps diversify CXW's revenue and cash flows into an adjacent business that management believes has significant runway to grow by adding new customers, including those that currently provide these services in-house, and potentially consolidating the business niche, combined with the anticipated growth of aging prison populations. Moreover, CXW expects its ability to provide a broader array of services to its government customers can enhance its opportunities and potentially create cross-selling opportunities. CSP has strong customer relationships, according to CXW. The company has indicated that it might explore at-home detention monitoring as another diversification into adjacent areas.
Strong balance sheet, substantial liquidity supports buybacks & growth measures
In our view, CXW has substantial liquidity to support operations, buybacks and growth measures. The company’s TTM Debt leverage ratio at the end of 3Q26 was (0.1)x, and CXW generates strong cash flow. Moreover, the company redeemed its senior notes due in 2027 and has de minimis debt maturities until 2029 and has enhanced its flexibility to repurchase shares and make tuck-in acquisitions, in our view. Reflecting the company's operating leverage, business momentum, and renewal rate on its facilities over the past five years (CXW has a 96.7% 5-year retention rate), among other factors, we are optimistic about CXW’s opportunity to continue generating stable cash flow.
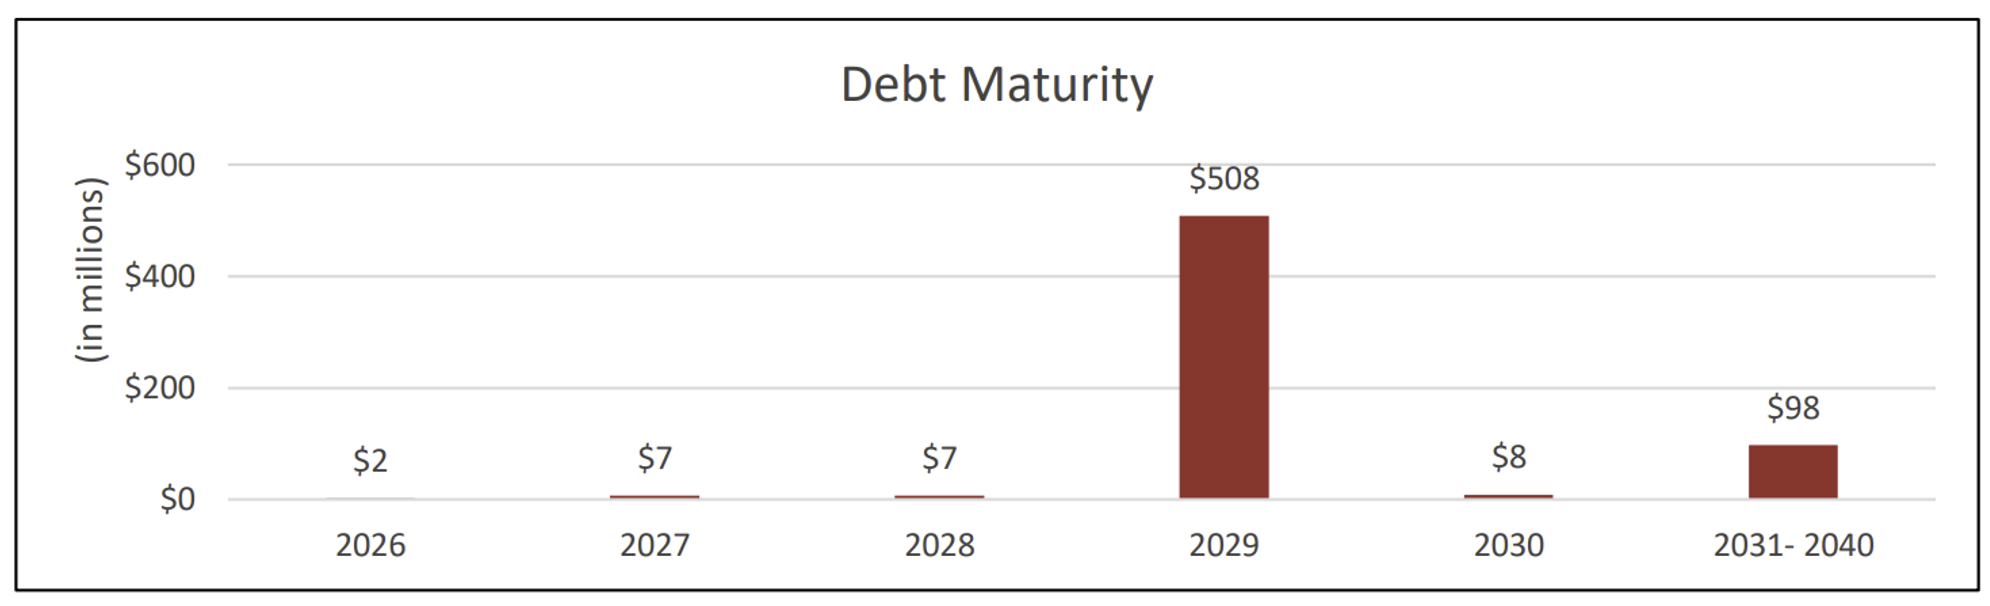
Source: Company presentation
SUBSCRIBE TO ZACKS SMALL CAP RESEARCH to receive our articles and reports emailed directly to you. Please visit our website for additional information on Zacks SCR.
DISCLOSURE: Zacks SCR has received compensation from the issuer directly, from an investment manager, or from an investor relations consulting firm, engaged by the issuer, for providing research coverage for a period of no less than one year. Research articles, as seen here, are part of the service Zacks SCR provides and Zacks SCR receives payments totaling a maximum fee of up to $50,000 annually for these services provided to or regarding the issuer. Full Disclaimer HERE.