By M. Marin
NASDAQ: HIT
READ THE FULL HIT RESEARCH REPORT
Contracted & Pipeline revenue: leading indicators to reflect momentum of HIT platform
Health in Tech (NASDAQ: HIT), an AI-enabled InsurTech platform, reported 2Q26 revenue of $8.1 million, compared to $9.3 million in 2Q25. The year-over-year decline primarily reflects the timing of onboarding new carriers, which shifted effective start dates of some policies forward. In 2Q26, HIT onboarded a new carrier partner and the effective dates of several policies shifted forward. When the company sells a policy, it does not recognize 100% of the revenue upfront, but ratably on a monthly basis over the 12- to 36-month life of the policy. The company noted that this equates to quarterly reported revenue being a lagging indicator of the momentum of its business, with contracted revenue — from policies that have been sold and are secured and will be recognized over the policy term — as the leading indicator.
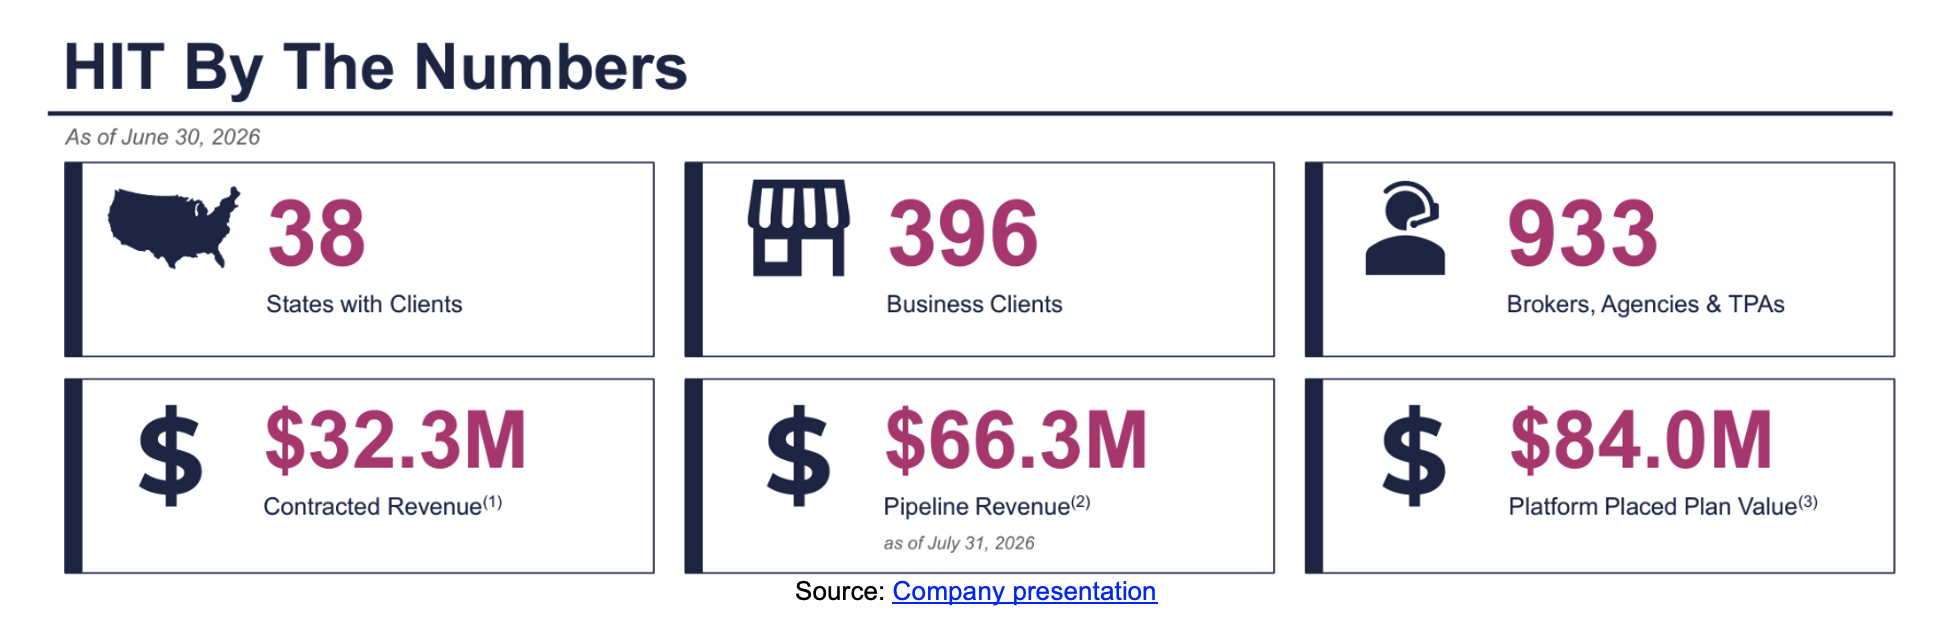
As of the end of 2Q26, total contracted revenue was $32.3 million, of which $17.3 million was recognized as GAAP revenue in 1H26. Another $14.0 million is expected to be recognized as GAAP revenue in 2H26 and $1.0 million in 2027. In addition, as HIT continues to engage with new and existing customers, extend its target market, expand its reach, and broaden its solutions offerings, pipeline revenue was $66.3 million at the end of 2Q26 (of this, $1.9 million became contracted revenue subsequent to the end of the quarter). The remaining $64.4 million represents policies that are being quoted or are in binding status. The company expects to realize a 15% to 40% conversion rate on pipeline revenue. The company believes these metrics are better indicators to reflect the momentum the company’s platform is experiencing.
The platform placed land value (PPLV) at 2Q26 was $84 million, up from $82 million at the end of the prior quarter. The PPLV represents the total contractual value of self-funded health plans with stop-loss insurance placed through the platform, covering the duration of the plans’ contractual term, which generally is 12 months from the plan’s effective date. The $84.0 million of self-funded stop-loss plans consists of self-funded health plans and bundled stop-loss premiums.
With 1st employer group for 3-year rate stabilization program secured pre-official launch & several high-profile organizations evaluating it, HIT is optimistic about its prospects
Importantly, prior to its actual commercial launch, HIT secured its first employer group under the 3-year rate stabilization program, which management believes offers proof of concept of the program’s prospects, as HIT prepares to introduce the program in the capital markets. The program is designed to eliminate fluctuations of healthcare costs, which HIT noted frequently is the 2nd largest expense for many organizations. It is designed to provide cost stability and predictability for employers. This potentially appeals to many large enterprises, in particular government agencies and municipalities, in order to secure multiyear budget certainty in annual healthcare costs. Several high-profile government organizations currently are evaluating participating in the 3-year rate stabilization program, and management is optimistic about its prospects.
HitRix set to launch officially in 2H26; Self-funded plans present sizable potential opportunity for growth
In addition, HIT is on track to launch HitRix officially in 2H26. The company believes the HitRix platform is the first comprehensive marketplace built for the large group self-funded stop-loss market. As noted in earlier reports, the self-funded stop-loss market generally is characterized by complexity that often makes it difficult for large employers to navigate and understand. It is also characterized by a manual, fragmented process, according to HIT, that has not been updated in decades. By comparison, the company’s existing platform, eDIYBS, serves the small group market, which is highly concentrated with only a few carriers offering stop-loss plans.
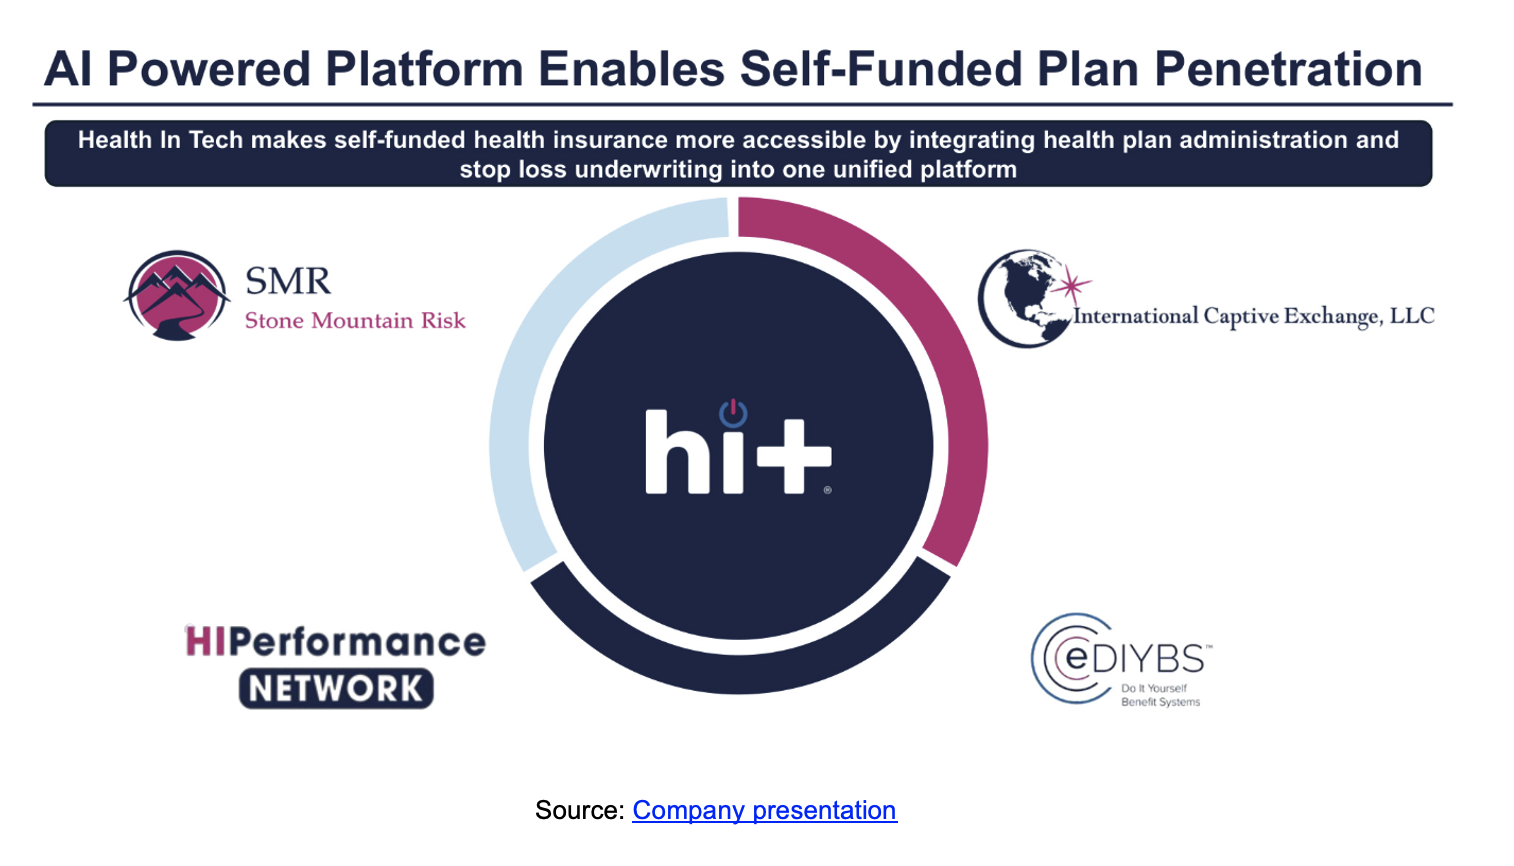
Reflecting interest it has generated to-date, the company is encouraged about its opportunities in the large-employer segment. HIT is optimistic about the traction it is seeing as it continues to engage with new and existing customers, extend its target market as it broadens its solutions offerings and expands its reach, and as it adds brokers and forms new relationships.
SUBSCRIBE TO ZACKS SMALL CAP RESEARCH to receive our articles and reports emailed directly to you. Please visit our website for additional information on Zacks SCR.
DISCLOSURE: Zacks SCR has received compensation from the issuer directly, from an investment manager, or from an investor relations consulting firm, engaged by the issuer, for providing research coverage for a period of no less than one year. Research articles, as seen here, are part of the service Zacks SCR provides and Zacks SCR receives payments totaling a maximum fee of up to $50,000 annually for these services provided to or regarding the issuer. Full Disclaimer HERE.